

Kikoff - Build Credit Quickly
Kikoff, Inc.
- 4.8
- 14.30K Reviews
- 1.00M
- Downloads
- Free
- Price
Screenshots
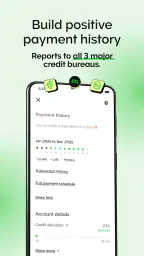
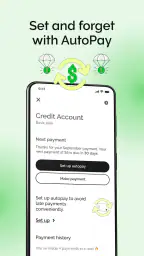
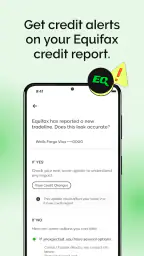
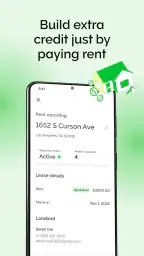
Kikoff - Build Credit Quickly Pros and Cons
Pros
- Easy to use interface
- Quick credit score updates
- Affordable subscription plans
- No hard credit checks
- Educational resources available
Cons
- Limited credit building options
- Requires bank account linking
- No physical credit card
- Slow customer support
- Limited to US residents
 Analysis by All-app
Kikoff is best approached as a focused way to explore credit building, not as a shortcut to a particular score. I like the idea of making credit feel less mysterious, but I’d be careful about expectations: building a credit history takes time, and an app cannot promise that every person’s score will change in the same way. If you’re considering Kikoff, the useful question is whether its approach fits your circumstances and whether you can keep up with the financial commitments involved.
What to consider before building credit with Kikoff
I’d use this section to look past the appeal of a low-friction starting point and judge whether a credit-building commitment fits my budget, timeline, and existing habits. A quick check of payment terms and reporting details can prevent an avoidable mismatch, especially when you’re preparing for a larger financial goal. That context makes it easier to weigh what Kikoff can realistically do against the alternatives.
A useful starting point, with realistic expectations
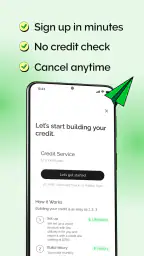
Kikoff is a finance app from Kikoff, Inc. It is free to download, has an Everyone age rating, and its store summary says that no credit check is needed. That last point may make it worth investigating if you have limited credit history or are cautious about applying for conventional credit products. I would still read the terms carefully before signing up: “no credit check” is not the same as “no obligations,” and it does not by itself explain how a credit-building arrangement works.
The app has an average rating of 4.8 from around 106,000 ratings, with about 14,000 written reviews, and has passed 1 million installs. Those figures suggest that many people have tried it, but they are not a substitute for checking whether its current terms suit you. Credit profiles differ, and user ratings cannot predict the result for your own file.
In practical terms, I’d treat any credit-building app as one part of a longer routine: understand what you agree to, make payments on time if payments are required, and review your credit information through appropriate channels. The aim is to establish consistent, responsible activity, not to chase a quick score jump. A person who already has missed payments or other issues may need a broader plan than a single app can provide.
How I’d fit it into an everyday routine
Imagine you’re starting a new job, have little credit history, and want to become more prepared before applying for an apartment or another financial product. I would first use the app to understand the commitment it asks for, then note any due dates in the same calendar I use for rent and utilities. I’d also set aside time each month to check that the payments I made are reflected as expected, rather than assuming that installing an app automatically improves a credit profile.
That routine matters because credit building is not only about signing up. It is also about avoiding missed payments, keeping track of what you owe, and giving positive activity time to accumulate. If you already manage several bills, adding another payment can create friction. Before enrolling, I’d decide exactly where the payment fits in my monthly budget and what reminder system I’ll use. A calendar alert or a recurring budgeting check can be more dependable than relying on memory.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
A second useful habit is to separate the app’s progress from your overall financial health. A credit score is only one measure, and a higher score does not make an unaffordable purchase sensible. If you are saving for a deposit or trying to reduce debt, those priorities may matter more than adding a new credit activity. I’d use the app only if its terms and payment schedule leave room for those essentials.
What the app’s positioning does—and does not—tell you
The no-credit-check message is a meaningful point of distinction for someone wary of applying for a conventional card or loan. It can lower one barrier to exploring the service, but it should not be read as a guarantee of approval for anything else, a promise of a score increase, or confirmation that every credit bureau or lender will treat your activity identically. Before making a decision, look for the specific terms describing what activity is reported, where it is reported, and how the arrangement can be ended.
This is where Kikoff differs from the usual alternatives in finance. A secured credit card generally involves using a deposit to support a card account; a conventional card depends on an application and its terms; and a credit-builder loan has its own repayment structure. These options can serve similar goals, but they are not interchangeable. I would compare the total cost, payment obligations, reporting details, and access to funds rather than choosing solely because one option sounds easiest to start.
If you already have a card that you can use responsibly and pay in full, adding another credit product may not be necessary. If you cannot reliably cover a new payment, I’d prioritize a budget and existing bills instead. Kikoff is more compelling for someone who wants to investigate a dedicated credit-building route and is comfortable reading the details before committing, rather than for someone expecting an effortless fix.
Small checks that can prevent bigger surprises
Before enrolling, I’d look for the payment amount and timing, any fees or other charges, the conditions for closing the account, and how customer support handles account-specific problems. Those details matter more than a polished dashboard. I would also save confirmation of the terms I accepted and keep an eye on statements or credit records afterward. This gives you a way to notice a discrepancy and ask a precise question rather than trying to reconstruct what happened months later.
Another practical point is to avoid applying for several products at once just because you are eager to establish credit. Even when an option says no credit check is needed, other applications may have separate processes and consequences. Make one decision at a time, understand what each product reports, and give your financial routine a chance to settle before adding more complexity.
If your goal is to prepare for a specific application, such as a rental or a car loan, start well before the deadline. Credit activity and reporting do not necessarily produce immediate results, and a service cannot guarantee that a lender will approve you. Kikoff may be part of a longer-term plan, but it should not be the only step you take to get ready for a near-term application.
Who is most likely to find it worthwhile
I’d consider Kikoff if I were new to credit, wanted to explore an option that does not require a credit check to get started, and could comfortably manage the terms after reviewing them. It may also appeal to someone who values having a dedicated place to think about credit habits rather than relying on a traditional card as the only route. The best fit is a patient user who pays attention to dates and terms, and who understands that progress depends on their circumstances and the way credit information is handled.
I’d be more cautious if I were already stretched by bills, uncertain about the costs, or looking for immediate access to spending money. It is also not the right choice for anyone who assumes that “build credit quickly” means a guaranteed score change by a fixed date. If you need advice about a complicated credit problem, a qualified nonprofit credit counselor or another appropriate professional may be more helpful than relying on an app alone.
Using the app without losing sight of the basics
One trade-off with any credit-focused service is that it can make score improvement feel like the whole goal. I would keep the broader picture in view: pay essential bills on time, avoid taking on payments you cannot afford, and check your credit information for accuracy. If you find an error, follow the relevant dispute process rather than assuming an app can correct it for you. A credit-building tool can support a habit, but it cannot replace careful money management or resolve every issue on a credit file.
I’d also revisit the decision after a few months instead of treating enrollment as permanent by default. Ask yourself whether the payment fits your budget, whether you understand the reporting, and whether the service is still helping with your actual goal. If the arrangement creates stress or the terms no longer make sense, reassess before continuing. That kind of periodic check is useful precisely because credit-building plans can outlast the circumstances that prompted them.
Getting started and deciding whether to continue
The app was released on March 25, 2021, and its current version is 1.141.2160; the listed minimum operating system is Android 7.0. Those details are useful when checking whether it is compatible with your device, but compatibility is only the first step. I’d still review the current in-app terms and make sure I understand the payment arrangement before entering into anything. An app update can change the interface, so I would rely on the terms presented when I sign up rather than assumptions based on an older description.
For someone comparing choices, I’d make a short checklist before installing: What exactly will I pay? When is it due? What activity is reported, and to whom? What happens if I miss a payment or want to stop? If the answers are clear and the arrangement fits your budget, trying a focused credit-building service may be reasonable. If you cannot get a clear picture of the commitment, pause and compare another option.
My take on the experience
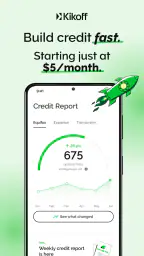
So, you’re ready to boost your credit score but don’t know where to start? Enter Kikoff. Signing up is a breeze – you just need to download the app, punch in some basic information, and voilà, you’re in! Once you've set up your account, the app offers a straightforward dashboard that displays all the essential information you need to track your credit-building journey.
Features that Make a Difference
One of the standout features of Kikoff is its ability to report to major credit bureaus. This means that every positive financial decision you make with the app can help improve your credit score. The app also provides a virtual credit line, allowing you to make purchases that are reported as positive credit activity.
Kikoff also offers educational resources to help users understand the ins and outs of credit building. Whether you're a newbie or someone looking to brush up on financial literacy, these resources are invaluable. They cover everything from how credit scores are calculated to tips on maintaining a healthy credit score.
User Experience: Smooth and Intuitive
Using Kikoff is like having a personal credit coach right in your pocket. The app’s interface is clean and intuitive, making it easy to navigate through the various features. Notifications are timely and helpful, ensuring that you never miss a payment or an opportunity to improve your credit score.
What I particularly love is the customer support – it's top-notch! Whether you have a simple question or need help with a complex issue, the support team is always ready to assist. This level of service makes a huge difference in keeping users motivated and on track with their credit goals.
Ending Thoughts
In today's world, having a good credit score can open doors to numerous financial opportunities. With Kikoff, building and maintaining a healthy credit score has never been easier. It's perfect for anyone looking to improve their credit standing without the hassle of traditional methods.
So, if you're looking to build credit quickly and efficiently, Kikoff is definitely worth considering. It's like having a financial ally that not only guides you but also grows with you on your credit journey. Give it a try, and watch your credit score soar!
Frequently Asked Questions
What is Kikoff and how does it help build credit quickly?
Kikoff is a financial app designed to help users build their credit scores efficiently. By offering a credit line and monitoring services, Kikoff enables users to make small, manageable monthly payments, which are then reported to major credit bureaus. This consistent reporting can help improve your credit score over time, making Kikoff a valuable tool for those looking to establish or enhance their credit history.
Is Kikoff suitable for individuals with no credit history?
Yes, Kikoff is particularly beneficial for individuals with limited or no credit history. The app provides a low-barrier entry point to begin building credit by offering a simple credit line. Users can start with small payments, which are reported to credit bureaus, thus helping them establish a credit record and improve their financial standing over time.
How much does it cost to use Kikoff?
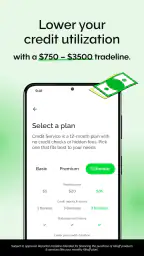
Kikoff offers a very affordable way to build credit, with their credit service costing just $2 per month. There are no hidden fees, annual charges, or interest rates associated with the service. This low-cost model makes it accessible to a wide range of users, providing an economical solution for those seeking to improve their credit scores without incurring significant costs.
How does Kikoff protect user data and ensure security?
Kikoff prioritizes user security by implementing robust encryption and data protection measures. The app uses industry-standard security protocols to safeguard personal and financial information. Regular security audits and updates are conducted to ensure the platform remains secure against potential threats, giving users peace of mind about their data's safety while using the app.
Can Kikoff negatively impact my credit score?
While Kikoff is designed to help build your credit score, it can negatively impact it if payments are missed or defaulted on. Just like any other credit product, responsible usage is key. Ensuring timely payments will help improve your credit score, whereas missed payments will be reported to credit bureaus and could potentially lower your score. Therefore, it's essential to manage your Kikoff account responsibly.


